THE ECONOMICS · 3 MIN READ
Discount spend vs incremental revenue: the $18 question
A $180 item, 10% off, and a $162 order. What can a merchant actually conclude—and what remains unknown?
What the receipt says
For a $180 item discounted by 10%, the arithmetic is straightforward:
| Listed price | $180 |
|---|---|
| Discount | −$18 |
| Customer paid | $162 |
The $18 is observed discount spend on this order. It is not automatically a $18 loss of profit, and the $162 is not automatically revenue created by the discount. Product costs, shipping, tax treatment, returns, and the unobserved full-price outcome all matter.
Two economic stories fit the same order
In one story, the shopper would have paid $180. The discount reduced the amount collected by $18 without creating an additional purchase. In the other, the shopper would not have purchased at $180, and the discounted offer contributed to a sale that otherwise would not have happened.
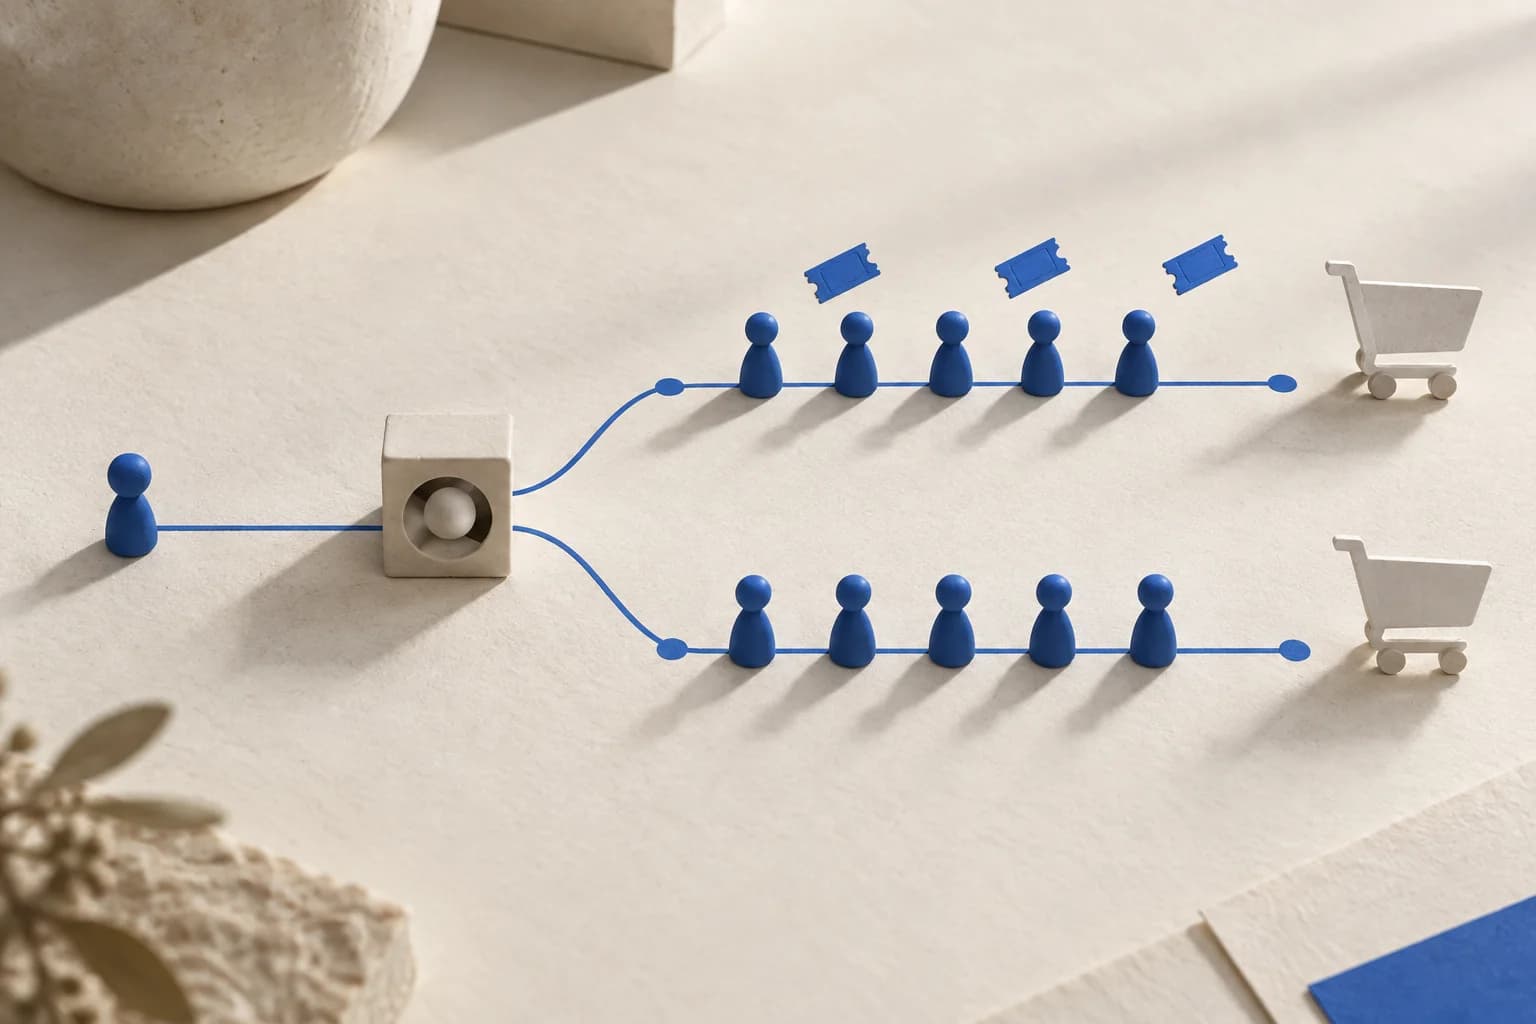
Neither story can be read from the receipt. Even customer intent scores or an abandoned-cart history do not observe the counterfactual. To estimate it, compare randomized groups of eligible shoppers. The incrementality guide explains why this is a population-level question.
Put every dollar over the right denominator
A campaign can cut total discount spend simply because fewer people purchased. That is not necessarily good news. Compare both arms per eligible shopper: purchases, revenue, and discount spend. This makes a conversion drop visible alongside the lower discount bill.
Suppose the no-offer arm spends $0 on experiment discounts. That is an observed cost difference. It becomes a favorable economic result only after the test also accounts for any change in orders, revenue, refunds, and—in a fuller margin analysis—reliable costs. Avoided spend is not a guaranteed saving.
The decision follows the measured difference
Predefine what would make the test mature, check that both arms received their intended treatment, and keep the uncertainty visible. If withholding the discount materially lowers conversion or revenue per eligible shopper, the discount may be earning its keep. If outcomes remain comparable within a decision rule and costs fall, the offer may be a candidate for restraint. A statistically inconclusive result is a reason to keep measuring, not to announce that discounts are unnecessary.
Next, see how to set up the 10% versus no-offer holdout and why refunds belong in the readout.
CONTINUE THE READING PATH